
By Rose Oswald Poels, WBA president and CEO
Each fall, WBA hosts a regulatory trip to Washington, D.C. to meet with regulator leadership to discuss concerns and share recommendations about regulation, guidance, and other supervisory actions directly affecting Wisconsin banks. Last week, 13 bankers joined WBA’s Heather MacKinnon, executive vice president and general counsel, and me in small group meetings with senior officials from the FDIC, Federal Reserve, OCC, CFPB, and SBA, where we discussed a wide range of issues.
 Our conversation with FDIC Chairman Travis Hill focused on the recent rulemaking activity by the agency regarding CAMELS rating reform, capital rule revisions, preemption, deposit insurance assessments, revised reciprocal deposit rules, CRA, and payment stablecoins. We encouraged FDIC to consider revising evaluation requirements of commercial real estate for loan renewals and requested FDIC to help fight fraud through investigating institutions who appear to have weak know-your-customer practices, create more consumer education pieces around fraud and fraud protection, and support revisions to Regulation CC rules to allow for longer holds on deposits to investigate fraud. Finally, we expressed our appreciation of FDIC’s change in supervision approach to focus examinations away from process-heavy checklists and instead to the review of those risks truly threatening safety and soundness.
In our conversation with Federal Reserve Special Counsel Aleksandra Wells, we recommended the agency take up joint rulemaking with CFPB to revise Regulation CC to allow for longer holds to investigate fraud-related activity. We also recommended the Fed join FDIC and OCC to revise their CRA rule and for the Fed to update their Consolidated Financial Statements for Holding Companies, FR Y-9C requirements to match the changes made last year to FDIC’s Part 363. We shared an example of harm caused to a bank by a large third-party core provider for its failure to deliver periodic statements to reinforce the need for agencies to hold core providers, and not the bank, responsible for the impact of the core’s actions and inactions. We also expressed appreciation for proposed revisions to modernize Regulation O.
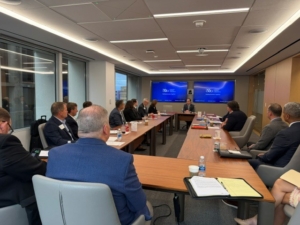
The focus of our meeting with Thomas R. Kimsey, Jr., SBA Associate Administrator, Office of Capital Access, was on recent changes made by SOP 50 10 8, to the 504 and 7(a) loan programs, and to modernize the E-Tran system. We discussed the need for improvement of their severe delay in SBA approval of outstanding guaranties, requested resurrection of a past floor-plan loan product, and expressed concerns over harm to SBA loan program availability due to default rates caused by careless underwriting practices by non-traditional lenders and credit unions engaged in SBA lending.
With senior officials from CFPB, our conversation focused on fraud. We encouraged CFPB to create consumer-facing resources and to engage in joint rulemaking with the Federal Reserve to revise Regulation CC to allow for longer holds on certain deposits, so banks have time to investigate fraud before funds leave the bank. We also expressed appreciation of the agency’s recent request for information regarding ways to improve mortgage-related disclosures and the loan-closing process.
We then joined bankers from the New England states for our conversation with OCC’s Acting Senior Deputy Comptroller for Consumer Banks, Stephen Lybarger. The discussion focused on OCC’s forthcoming final rule regulating payment stablecoin issuers. We were frustrated to hear of OCC’s “wait-and-see” approach to the concerns of bankers over the impact of payment stablecoins on bank core deposits, given the possibility of the payment of yield, rewards, or incentives through payment stablecoin-affiliated platforms.
I would like to thank the following bankers for joining WBA this year: Al Araque, Johnson Financial Group; Scott Cattanach, Peoples State Bank; Ami Dregne, Citizens First Bank; Kristen Gagliano, North Shore Bank; Laura Garcia, First Business Bank; Corey Hoze, Associated Bank; Ryan Kamphuis, Bristol Morgan Bank; Jimmy Kauffman, Bank of Sun Prairie; Gary Kuter, Bank of Sun Prairie; Jeff Langkamp, Bank Five Nine; Nate Parrish, First Citizens State Bank; Tim Siegel, Bank Five Nine; Lisa Weeks, Bristol Morgan Bank; and Dave Feldhaus, FHLBank of Chicago.
Amplify Your Voice – PARTICIPATE!
Each year WBA hosts three Washington, D.C. fly-ins, two in the spring and one in the fall. The spring trips involve meetings with Wisconsin’s Congressional delegation. The fall trip focuses on meeting with regulators. As stated above, these meetings are impactful as bankers can speak directly with decision makers and influencers regarding banking issues. I highly encourage you to consider attending either our Spring Hill visits, scheduled for March 8–10, 2027, or April 26–29, 2027, or next year’s fall regulatory trip!


