• Home
  • Education
  • News and Resources
  • Advocacy
  • Associate Members
  • Contact
  • My Profile
  • Click to open the search input field Click to open the search input field Search
  • Menu Menu

Tag Archive for: Regulatory News

Posts

News

Potential Impact of Executive Orders on Community Banks

In what was has been a busy first week for the new administration with the release of numerous Executive Orders (EOs) from the White House, several EOs have a direct or indirect impact on community banks. The following is a highlight of several orders and their anticipated or potential impact. 

One of the most significant EOs to the industry is titled, Regulatory Freeze Pending Review, whereby government agencies may not propose or issue any rule, including sending it to the Office of the Federal Register (OFR), until a department or agency head reviews and approves the rule. The Director or Acting Director of the Office of Management and Budget (OMB) has the ability to exempt any rule from the EO deemed necessary to address emergency or other urgent situations. Rules which had been sent to OFR but not yet published are to be withdrawn for review and approval.  

Additionally, the agencies are to consider postponing for 60 days the effective date of any rule that had been published in the Federal Register but had not yet taken effect for the purpose of reviewing any questions of fact, law, and policy that the rules may raise. During the 60-day period, where appropriate and consistent with applicable law, the agencies are to consider opening a comment period to allow interested parties to provide comments about issues of fact, law, and policy raised by the rules postponed, and consider reevaluating pending petitions involving such rules. The 60-day period may be extended, where appropriate and consistent with applicable law. Use of the word “rule” within the EO includes guidance, advanced notice of proposed rulemaking, notices, proposed and final rules. A pause on regulation is common when administrations change.  

Equally significant are EOs which Designate Chairmen and Acting Chairmen, Acting Cabinet and Cabinet Level Positions, Sub-Cabinet Appointments, and Cabinet and Cabinet-Level Appointments. Through the series of these orders, key leadership designations and appointments for agencies have been made allowing affected industries to begin anticipating the interests, priorities, and perspectives of agency and department heads. Designations and nominations include: 

  • Travis Hill, Acting Chairperson of the Board of Directors of Federal Deposit Insurance Corporation 
  • Andrew Ferguson, Chair of Federal Trade Commission 
  • Mark Uyeda, Acting Chair of Securities and Exchange Commission 
  • Jeffrey Hall, Chair of Farm Credit Administration Board, Farm Credit Administration   
  • David Lebryk to act as Secretary of Treasury, Scott Bessent nominated as Secretary of Treasury  
  • Gary Washington to act as Secretary of Agriculture, Brooke Rollins nominated as Secretary of Agriculture 
  • Everett Woodel to act as Administrator of Small Business Administration, Kelly Loeffler nominated as Administrator of Small Business Administration 
  • Matthew Ammon to act as Secretary of Housing and Urban Development, Eric Turner nominated as Secretary of Housing and Urban Development 
  • Ingrid Kolb to act as Secretary of Energy, Christopher Wright nominated as Secretary of Energy 
  • Matthew Vaeth to act as Director of OMB, Russell Vought nominated as Director of OMB 

Wisconsin is represented in the nomination of persons serving on a national level with Sean Duffy having been nominated as Secretary of Transportation.  

 In an EO titled, Initial Rescission of Harmful EOs and Actions, seventy-eight EOs from the previous administration stretching from 2021 to last week were rescinded. Within the list rescinded was EO 14030 from May 2021 regarding Climate-Related Financial Risk. In the 2021 order, financial institutions were criticized for the “failure…to appropriately and adequately account for and measure…” the impact of extreme weather risk resulting in supply chain disruptions. The order required the Financial Regulators to conduct an assessment which included a determination of how identified climate-related financial risk can be mitigated, including through new or revised regulatory standards. These efforts resulted in several new burdensome and costly requirements, such as SEC investor disclosures about climate-related risks, emissions, and targets for public companies, including banks.  

Another notable order rescinded was EO 14110: Safe, Secure, and Trustworthy Development and Use of Artificial Intelligence (AI) from October 2023, which encouraged creating AI-related policies which promoted responsible innovation, competition, and collaboration while being safe and secure.  

Other EOs rescinded by the new order included topics of diversity, equity, inclusion, and accessibility (DEI), immigration, and energy-related issues involving oil, gas, wind, and water uses. The rescissions will likely affect community banks from the standpoint of their impact on their customer base, e.g., business customers whose employee base include immigrants, customers with a connection to energy and energy-related fields, and potentially in DEI-related efforts. Other energy-related EOs (Declaring a National Energy Emergency, Unleashing Alaska’s Extraordinary Resource Potential, Unleashing American Energy) will also impact customers in such industries with new or revised business needs.  

Through the America First Trade Policy  EO, the new administration seeks to prioritize domestic production and reduce trade-related uncertainties. This policy could influence credit demands in local markets. Community banks may see changes in small-business borrowing trends as industries adapt to a new trade environment. New employment opportunities may also be experienced as businesses expand to meet new or increased product and service demands.  

As a result of the Delivering Emergency Price Relief for American Families and Defeating the Cost of Living Crisis EO, department and agency heads are to deliver emergency price relief through:   

  • Lowering the cost of housing and expanding the housing supply  
  • Eliminating administrative expenses and rent-seeking practices that increase healthcare costs  
  • Eliminating requirements that raise the costs of home appliances  
  • Creating employment opportunities for American workers and draw discouraged workers into the workforce  
  • Eliminating climate policies that increase the costs of food and fuel  

While the executive order aims to reduce costs and stimulate economic activity, its success depends on implementation and broader market responses. These cost savings should impact deposit balances and lending needs with customers having greater purchasing power from the savings reflected in lowered living costs.  

Several EOs directly affect federal agencies whereby each are to find efficiencies, freeze hiring, and return to the office. An order establishing the President’s Department of Government Efficiency (DOGE), the department, together with the OMB Director, is required to submit a plan within 90 days to reduce the size of the Federal Government’s workforce through efficiency improvements and attrition, at which point the hiring freeze will be lifted except for the IRS, for which the freeze is indefinite.  

Within this DOGE EO there is a mandate regarding Modernizing Federal Technology and Software to Maximize Efficiency and Productivity. Potential positive benefits to community banks include if federal agencies “improve quality and efficiency of government-wide software, network infrastructure, and information technology (IT) systems. Among other things, the United States Digital Services Administrator shall work with Agency Heads to promote inter-operability between agency networks and systems, ensure data integrity, and facilitate responsible data collection and synchronization.”  

The Hiring Freeze EO directs agencies not to fill any vacant federal positions or create any new roles (with exceptions for military personnel and positions related to immigration enforcement, national security, or public safety). By freezing new hires across federal agencies, including those overseeing financial regulation, this order could create operational bottlenecks for community banks seeking regulatory guidance, delay examinations, and cause delays in processing and disbursement of government-backed loans. Impact will depend on how long the freeze remains in effect and whether exemptions are granted for key regulatory and operational positions. Community banks should prepare for potential delays and adjust their interactions with federal banking agencies accordingly. Community banks will also notice a change in federal regulator staff locations as federal employees have been ordered to end remote work and Return to Work In-Person at their respective duty stations on a full-time basis as soon as practicable, unless an exemption is necessary.  

The EO issued last Thursday, Strengthening American Leadership in Digital Financial Technology, will have a significant impact on community banks. While promoting and protecting fiat currency, the EO seeks to bring regulatory clarity of digital assets. For purpose of the order, “digital asset” refers to any digital representation of value that is recorded on a distributed ledger, including cryptocurrencies, digital tokens, and stablecoins. The order defines “Central Bank Digital Currency (CBDC)” as a form of digital money or monetary value, denominated in the national unit of account, that is a direct liability of the central bank. The term “blockchain” means any technology where data is:  

  • Shared across a network to create a public ledger of verified transactions or information among network participants; 
  • Linked using cryptography to maintain the integrity of the public ledger and to execute other functions;  
  • Distributed among network participants in an automated fashion to concurrently update network participants on the state of the public ledger and any other functions; and 
  • Composed of source code that is publicly available. 

This order revokes EO 14067: Ensuring Responsible Development of Digital Assets and the Treasury’s “Framework for International Engagement on Digital Assets” both from 2022. Treasury is also ordered to rescind all policies, directives, and guidance issued pursuant to the 2022 order and framework.  

Further, the order establishes the National Economic Council the President’s Working Group on Digital Asset Markets to be chaired by the Special Advisor for AI and Crypto. The working group is also to include the Secretary of the Treasury, Attorney General, Secretary of Commerce, Secretary of Homeland Security, OMB Director, Assistant to the President for National Security Affairs, Assistant to the President for National Economic Policy, Assistant to the President for Science and Technology, Homeland Security Advisor, Chairman of the SEC, and Chairman of the CFTC. 

Within 30 days of the order, certain agencies are to identify all regulations, guidance documents, orders, or other items that affect the digital asset sector. Within 60 days, each are to submit recommendations on whether each identified regulation, guidance document, order, or other item should be rescinded or modified, or, for items other than regulations, adopted in a regulation. Within 180-days, a report is to be made to the President which is to recommend regulatory and legislative proposals that advance the policies established in the order. In particular, the report is to:  

  • Propose a Federal regulatory framework governing the issuance and operation of digital assets, including stablecoins, in the United States. The report is to consider provisions for market structure, oversight, consumer protection, and risk management. 
  • Evaluate the potential creation and maintenance of a national digital asset stockpile and propose criteria for establishing such a stockpile, potentially derived from cryptocurrencies lawfully seized by the Federal Government through its law enforcement efforts. 

The working group is to hold public hearings and receive individual expertise from leaders in digital assets and digital markets. Additionally, except to the extent required by law, agencies are prohibited from undertaking any action to establish, issue, or promote CBDCs within the jurisdiction of the United States or abroad. Any ongoing plans or initiatives at any agency related to the creation of a CBDC within the jurisdiction of the United States is immediately terminated, and no further actions may be taken to develop or implement such plans or initiatives.  

The WBA Legal, Government Relations, and Communications teams will continue to monitor EOs issued by the new administration, and report on such matters accordingly. WBA will remain engaged with all federal agencies through the efforts started by the EOs, including in the most recent digital asset order. Any questions regarding the executed orders may be directed to WBA Legal at wbalegal@wisbank.com
January 27, 2025/by Katie Reiser
https://www.wisbank.com/wp-content/uploads/2021/09/Triangle-Backgrounds_Yellow-on-Light-Blue.jpg 972 1921 Katie Reiser https://www.wisbank.com/wp-content/uploads/2021/09/Wisconsin-Bankers-Association-logo.svg Katie Reiser2025-01-27 08:54:312025-01-27 08:55:11Potential Impact of Executive Orders on Community Banks
Compliance

Executive Letter: Share Your Experiences Regarding Burdensome Regulations

By Rose Oswald Poels

The federal bank regulatory agencies are seeking comment on interagency efforts to reduce regulatory burden: the Federal Deposit Insurance Corporation (FDIC); the Federal Reserve Board (FRB), and the Office of the Comptroller of the Currency (OCC).

Anyone working in banking knows that it is one of the most highly regulated industries in the country. While we certainly respect the need for regulations aimed at protecting consumers, preventing bank failures, and promoting stability in our nation’s financial system, this opportunity to comment on regulatory burden is welcome.

The Economic Growth and Regulatory Paperwork Reduction Act of 1996 (EGRPRA) requires the Federal Financial Institutions Examination Council (FFIEC) and federal bank regulatory agencies to review their regulations every ten years to identify outdated or otherwise unnecessary regulatory requirements for their supervised institutions.

To facilitate this review, the agencies divided their regulations into 12 categories (in alphabetical order):
• Applications and Reporting
• Banking Operations
• Capital
• Community Reinvestment Act
• Consumer Protection
• Directors, Officers, and Employees
• International Operations
• Money Laundering
• Powers and Activities
• Rules of Procedure
• Safety and Soundness
• Securities

The agencies are now soliciting comments on their regulations in three categories: Consumer Protection; Directors, Officers, and Employees; and Money Laundering. The public has 90 days from publication in the Federal Register to comment on the relevant regulations.

On February 6, 2024, the agencies published the first notice addressing the following categories of regulations: Applications and Reporting; Powers and Activities; and International Operations. The comment period for those categories closed on May 6, 2024.

Over the next two years, the agencies will request comment on regulations in the remaining categories, asking the public to identify the regulations they believe are outdated, unnecessary, or unduly burdensome. The agencies will review the comments received and determine whether further action is appropriate with respect to the regulations.

WBA will be sharing comments in response to this interagency request. It is crucial to amplify the voice of bankers in Wisconsin who are dealing with unnecessarily onerous regulatory requirements. Please contact me to share stories of how your bank is impacted by regulations from FDIC, FRB, and OCC in the categories of Consumer Protection; Directors, Officers, and Employees; and Money Laundering that could be described as outdated, unnecessary, or unduly burdensome as well as suggestions on how to ease those burdens. It is incredibly helpful to get input from WBA members, so I welcome the frank assessments, common sense strategies, and practical potential solutions provided by leaders of Wisconsin’s banking industry.

In related news, the agencies are holding a virtual public outreach meeting on September 25, 2024, as part of their review.

The Economic Growth and Regulatory Paperwork Reduction Act Virtual Outreach Meeting is an opportunity for interested stakeholders to present their views on the six categories of regulations listed in the first two Federal Register notices (described above): Applications and Reporting; Powers and Activities; International Operations; Consumer Protection; Directors, Officers and Employees; and Money Laundering.

Individuals interested in providing oral comments need to register by August 9, 2024, and indicate the regulatory category they would like to discuss. The agencies will notify those individuals selected to provide comments by September 9, 2024. Click here to register.

Advance registration is not required to attend this virtual public meeting as an observer.

The agencies will announce additional public meetings in 2024 and 2025. Details will be available on the EGRPRA website.

Since this request for input on regulatory burden in our industry only occurs every ten years, I encourage you to take advantage of this opportunity and share your insights.

August 1, 2024/by Katie Reiser
https://www.wisbank.com/wp-content/uploads/2021/09/Triangle-Backgrounds_Yellow-on-Light-Blue.jpg 972 1921 Katie Reiser https://www.wisbank.com/wp-content/uploads/2021/09/Wisconsin-Bankers-Association-logo.svg Katie Reiser2024-08-01 08:06:282024-08-01 08:06:28Executive Letter: Share Your Experiences Regarding Burdensome Regulations
Compliance, News

Executive Letter: 2024 Brings Adjusted Regulatory Thresholds

By Rose Oswald Poels

Happy New Year! As we step into 2024, there are several thresholds which have been adjusted by both state and federal regulators which go into effect now that the new year has arrived. Below is a collection of thresholds effective January 1, 2024, including a link to pull each publication for reference.

Regulation Z, TILA

  • The exemption threshold for Regulation Z (Truth in Lending Act) will increase to $69,500, up from $66,400.
  • The exemption threshold under Regulation Z for HPML appraisals will increase to $32,400, up from $31,000.
  • The asset-size threshold under Regulation Z which exempts creditors from the requirement to establish an escrow account for HPMLs will be:
    • For creditors and their affiliates that regularly extended covered transactions secured by first liens, the asset-size threshold is adjusted to $2.640 billion, up from $2.537 billion; and
    • The exemption threshold for certain insured depository institutions with assets of $10 billion or less is adjusted to $11.835 billion, up from $11.374 billion.
  • The dollar amount thresholds under Regulation Z for HOEPA and QM-related loans have been adjusted as follows:
    • For HOEPA loans, the adjusted total loan amount threshold for high-cost mortgages will be $26,092.
    • The adjusted points-and-fees dollar trigger for high-cost mortgages will be $1,305.
    • For QMs under the General QM loan definition in § 1026.43(e)(2), the thresholds for the spread between the annual percentage rate (APR) and the average prime offer rate (APOR) will be:
      • 2.25 or more percentage points for a first-lien covered transaction with a loan amount greater than or equal to $130,461;
      • 3.5 or more percentage points for a first-lien covered transaction with a loan amount greater than or equal to $78,277 but less than $130,461;
      • 6.5 or more percentage points for a first-lien covered transaction with a loan amount less than $78,277;
      • 6.5 or more percentage points for a first-lien covered transaction secured by a manufactured home with a loan amount less than $130,461;
      • 3.5 or more percentage points for a subordinate-lien covered transaction with a loan amount greater than or equal to $78,277; or
      • 6.5 or more percentage points for a subordinate-lien covered transaction with a loan amount less than $78,277.
    • For all categories of QMs, the thresholds for total points and fees will be:
      • 3% of the total loan amount for a loan greater than or equal to $130,461;
      • $3,914 for a loan amount greater than or equal to $78,277 but less than $130,461;
      • 5% of the total loan amount for a loan greater than or equal to $26,092 but less than $78,277;
      • $1,305 for a loan amount greater than or equal to $16,308 but less than $26,092; and
      • 8% of the total loan amount for a loan amount less than $16,308.
  • For open-end consumer credit plans under TILA, the threshold that triggers requirements to disclose minimum interest charges will remain unchanged at $1.00.

Regulation C, HMDA

  • The asset-size threshold to be exempt from collecting HMDA data in 2023 is adjusted to $56 million, up from $54 million.

Community Reinvestment Act (CRA)

  • The Board of Governors of the Federal Reserve System (FRB) and Federal Deposit Insurance Corporation (FDIC) CRA regulations have adjusted the asset-size thresholds used to define “small bank” and “intermediate small bank” to be:
    • Small bank means a bank that, as of December 31 of either of the prior two calendar years, had assets of less than $1.564 billion; and
    • Intermediate small bank means a small bank with assets of at least $391 million as of December 31 of both of the prior two calendar years and less than $1.564 billion as of December 31 of either of the prior two calendar years.
  • The Office of the Comptroller of the Currency (OCC) made the identical adjustments to the asset-size thresholds used to define “small bank or savings association” and “intermediate small bank or savings association.”

Required Escrow Rate Under Wisconsin Law

  • The Wisconsin Department of Financial Institutions (WDFI) has established the interest rate that must be paid on required escrow accounts under section 138.052(5) of the Wisconsin Statutes. The new rate is 0.18%.

Other Regulatory Thresholds and Limits

  • The dollar amount of the maximum allowable charge for disclosures by a consumer reporting agency to a consumer pursuant to Fair Credit Report Act (FCRA) section 609 for the 2024 calendar year is $15.50.
  • The exemption threshold for Regulation M (Consumer Leasing Act) will increase to $69,500, up from $66,400.
  • The FDIC Designated Reserve Ratio remains 2% for 2024.
  • The OCC is maintaining the general assessment, independent trust, and independent credit card fee schedules from 2023. There will be no inflation adjustment to assessment rates. OCC is increasing the hourly fee for special examinations and investigations to $170 from $161. The increase is to ensure adequacy in recovering the cost of conducting special examinations and investigations.
  • Contribution limit for employees who participate in 401(k), 403(b), most 457 plans, and the federal government’s Thrift Savings Plan is increased to $23,000, up from $22,500. The limit on annual contributions to an IRA increased to $7,000, up from $6,500.
  • Multifamily loan purchase caps for Fannie Mae and Freddie Mac will be $70 billion for each enterprise, for a combined total of $140 billion. The caps reflect current market forecasts. FHFA will continue to require that at least 50% of Fannie’s and Freddie’s multifamily business be mission-driven affordable housing.
  • The conforming loan limit values for mortgages to be acquired by Fannie Mae and Freddie Mac in 2024 for one-unit properties will be $766,550, an increase from $726,200.
  • New loan limits for FHA’s Single Family Title II Forward and Home Equity Conversion Mortgage (HECM) insurance programs, based upon property size and location, range from $498,257 to $3,317,400.
  • Beginning January 1, 2024, the standard IRS mileage rates for the use of a car (also vans, pickups, or panel trucks) will be as follows. The rates apply to electric and hybrid-electric automobiles, as well as gasoline and diesel-powered vehicles.
    • 67 cents per mile driven for business use, up 1.5 cents from 2023;
    • 21 cents per mile driven for medical or moving purposes for qualified active-duty members of the Armed Forces, a decrease of 1 cent from 2023; and
    • 14 cents per mile driven in service of charitable organizations; the rate is set by statute and remains unchanged from 2023.

I look forward to this new year and am excited about what 2024 may bring. Be sure to stay connected with WBA through our various releases and publications, and through our social media channels.

January 2, 2024/by Hannah Flanders
https://www.wisbank.com/wp-content/uploads/2021/09/Untitled-3_Yellow.jpg 972 1920 Hannah Flanders https://www.wisbank.com/wp-content/uploads/2021/09/Wisconsin-Bankers-Association-logo.svg Hannah Flanders2024-01-02 10:44:592024-01-02 11:10:03Executive Letter: 2024 Brings Adjusted Regulatory Thresholds
Advocacy, News

Executive Letter: Regulatory Advocacy in Action

By Rose Oswald Poels

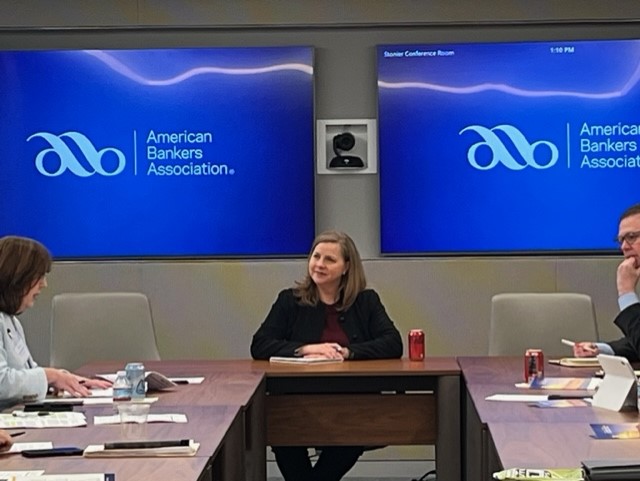
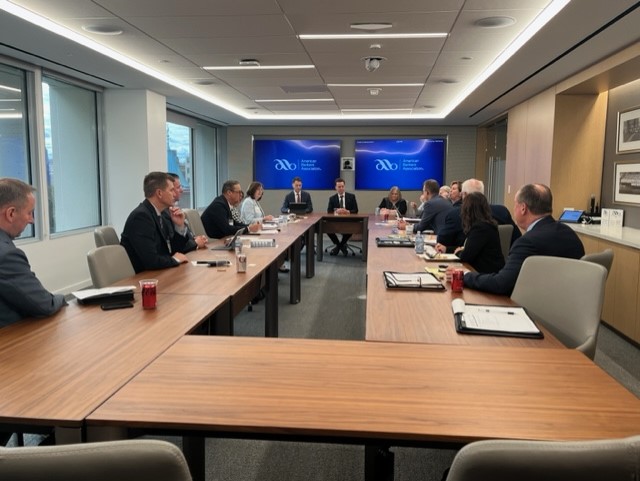
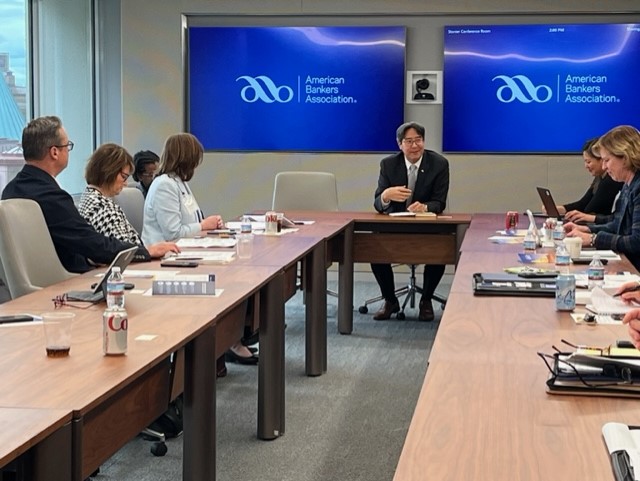
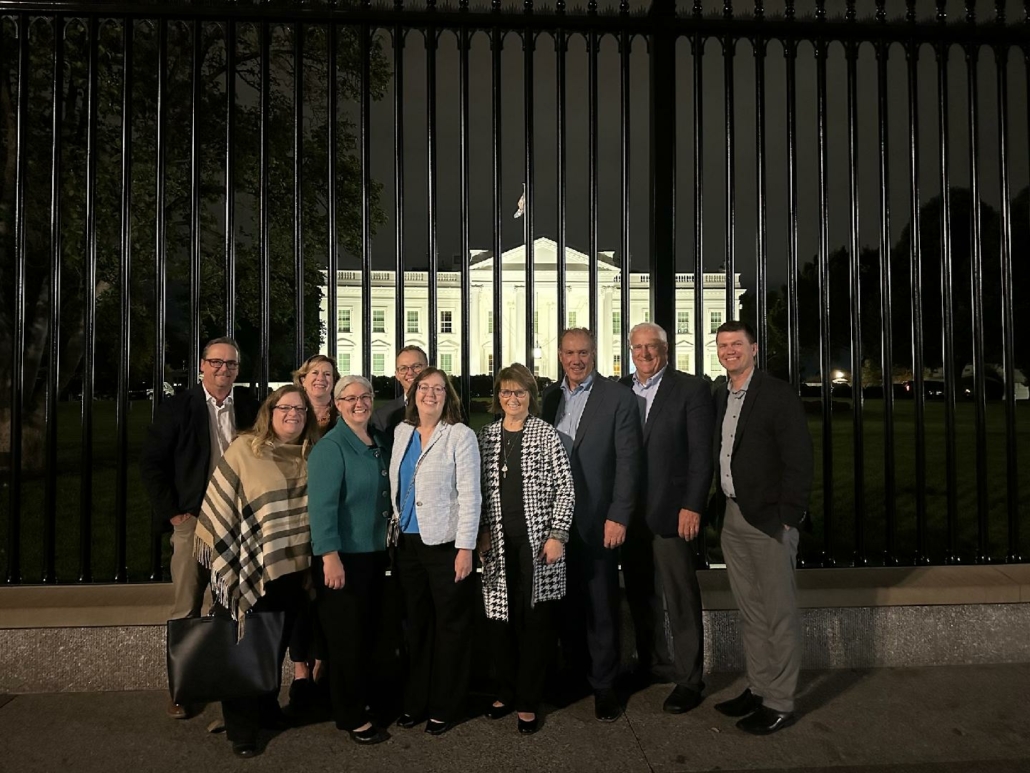
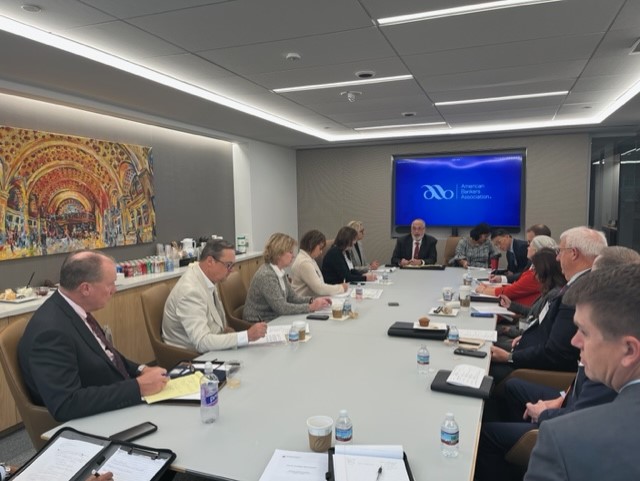
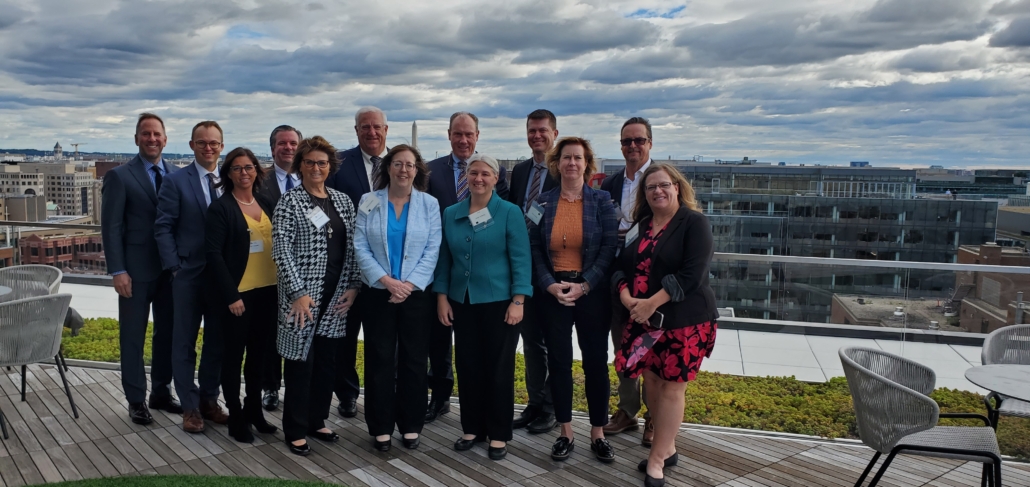
Last week, 12 bankers joined WBA’s Heather MacKinnon, VP – legal, and me in Washington, D.C. for our annual trip to meet with regulators. This trip is always a productive one, resulting in impactful advocacy and conversations given the smaller group size. In the span of only two half-days, our group was able to meet with senior officials from the Federal Reserve, FDIC, OCC, CFPB, FinCEN, and FHFA. The topics we covered in detail included representment fees, bank capital/liquidity, Section 1071, Section 1033, beneficial ownership, FHLB reform, cybersecurity, and other top examination concerns.

Our conversation with Fed Governor Miki Bowman focused on the Fed’s recent compliance bulletin published last month noting that Fed member banks are now being cited with an unfairness UDAP violation if they are charging representment fees. This retroactive application of the Fed’s new expectation as it relates to these fees is creating results that are unjust and wrong. Furthermore, it is also wrong to be creating new rules for banks to follow through the mere issuance of a compliance publication rather than following the formal Administrative Procedures Act rulemaking process. Governor Bowman was surprised to hear of the retroactive nature of these exam findings and agreed to continue to talk with WBA and affected banks about the matter. If you are a Fed member bank and have received a similar finding in your recent exam reports, please let me know and we will include you in our follow-up conversations with the Fed.

Back in April of 2022 when the FDIC first published its new expectations regarding NSF and representment fees in a guidance document, many bankers and trade associations including WBA advocated against any retroactive application of their new interpretation, among other concerns. This resulted in the FDIC eventually adjusting its focus in exams to be prospective only in nature, and to our knowledge did not cite anyone for an unfairness UDAP violation. In our conversations last week with senior FDIC officials, it sounded as though the FDIC may now begin issuing unfair UDAP violations as well. FDIC Director Jonathan McKernan also shared his thoughts with our group around lessons learned from the bank failures earlier this year, encouraged bankers and WBA to comment on the impact the BASEL capital proposal could have on mortgage operations, and supported the role of community banks in fostering an innovative economy.

Previous Previous Previous Next Next Next
123456
Fed Governor Miki Bowman Open image in lightbox: Fed Governor Miki Bowman Open image in lightbox: Fed Governor Miki Bowman
FDIC Director Jonathan McKernan Open image in lightbox: FDIC Director Jonathan McKernan Open image in lightbox: FDIC Director Jonathan McKernan
OCC Acting Comptroller Michael Hsu Open image in lightbox: OCC Acting Comptroller Michael Hsu Open image in lightbox: OCC Acting Comptroller Michael Hsu
Group photo outside White House Open image in lightbox: Group photo outside White House Open image in lightbox: Group photo outside White House
CFPB senior officials Open image in lightbox: CFPB senior officials Open image in lightbox: CFPB senior officials
Group photo on rooftop Open image in lightbox: Group photo on rooftop Open image in lightbox: Group photo on rooftop

Much of the focus of our conversation with OCC Acting Comptroller Michael Hsu was on safety and soundness matters, including the need for banks to stress test their liquidity contingency funding plans and analyze how “sticky” and stable banks’ deposits really are.

With senior officials from CFPB, among other topics, we stressed the industry’s frustration with the Agency’s and Administration’s continued use of “junk fees” to describe fees that are fully disclosed in transparent ways — often on bank websites — in advance to consumers. We discussed beneficial ownership operational concerns at length with FinCEN officials, and learned from the FHFA that their document on FHLB reform will be released “soon.” Overall, the conversations with all six agencies were very productive.

I would like to thank the following bankers for joining WBA this year: Adam Bellmer, Johnson Financial Group; Dave Feldhaus, Federal Home Loan Bank of Chicago; Kristen Gagliano, North Shore Bank; Donna Hoppenjan, Mound City Bank; Corey Hoze, Associated Bank; Caryn Langolf, Bank First; Tom Mews, First National Community Bank; Ryan Kamphuis, Bristol Morgan Bank; Greg Ogren, Security Bank Shares; Dan Peterson, The Stephenson National Bank and Trust; John Udvare, The Equitable Bank; and Theresa Wiese, First Business Bank. If you are interested in joining WBA on this trip next October, please let me know!

October 25, 2023/by Hannah Flanders
https://www.wisbank.com/wp-content/uploads/2021/09/Triangle-Backgrounds_Blue-on-Lime-Green.jpg 972 1920 Hannah Flanders https://www.wisbank.com/wp-content/uploads/2021/09/Wisconsin-Bankers-Association-logo.svg Hannah Flanders2023-10-25 15:52:222023-10-25 15:53:01Executive Letter: Regulatory Advocacy in Action
Desk with gavel and scales
Compliance, News

Compliance Column: A Refresher on Rescission Rules

By Scott Birrenkott

One of the consumer protection rights afforded by Truth in Lending is the right of rescission. While there are no changes to this rule, it is a frequent topic for questions received through the Wisconsin Bankers Association’s (WBA) Legal Call Program. It is important that bankers understand and consider various aspects of this rule.

The right of rescission can be found under Regulation Z for both closed-end and open-end credit. Generally speaking, rescission applies in a credit transaction secured by a consumer’s principal dwelling. For purposes of rescission, each consumer whose ownership interest is subject to the security interest shall have the right to rescind the transaction, unless exempt.

One of the most common questions WBA receives is: who gets rescission?

All consumers receive the right of rescission. Reg Z defines consumer as a natural person to whom consumer credit is offered or extended. However, for purposes of rescission, the term also includes a natural person in whose principal dwelling a security interest is, or will be, retained or acquired, if that person’s ownership interest in the dwelling is or will be subject to the security interest. In short, any consumer with an ownership interest in the dwelling taken as security receives the right of rescission. This could include a non-borrower.

For example, consider a situation where a borrower’s parents pledge their house as security for a covered transaction. The parents are not borrowers and thus, not obligated to the transaction. However, because their ownership interest in the house is subject to the security interest, they must be provided with the right of rescission.

It is also worth noting that sometimes a trust can be considered a consumer for purposes of rescission. Credit extended to trusts established for tax or estate planning purposes or to land trusts is considered to be extended to a natural person for purposes of the definition of consumer. In the case where the property is held by a trust, lenders should make sure to review Reg Z to see whether the trust might be a consumer for purposes of rescission.

Another common question WBA receives is whether a consumer can waive the right to rescind. In certain rare circumstances this is possible, but only in the case of a bona fide personal financial emergency.

The rule does not provide examples, but the situation must present a true emergency. For example, during the COVID pandemic, there may have been truly bona fide personal financial emergencies which warranted a need to receive credit without a waiting period. As a result, whether such an emergency exists is a fact-specific question. WBA has heard of situations where the borrowers are going on vacation and want to close without a waiting period, or where the seller is growing anxious and does not want to wait any longer. Such situations are not emergencies. A true, bona fide financial emergency must exist for it to be possible to waive rescission.

While rescission is not a new rule nor have there been any changes, the above article covers some of the more frequently asked questions.

For reference, also consider the following citations to Regulation Z:

  • Rescission for open-end-credit: 1026.15
  • Rescission for closed-end-credit: 1026.23
  • Definition of consumer: 1026.2(a)(11)
  • Discussion of trusts, which may be a consumer, for purposes of rescission: 1026.3(a)-10
October 3, 2023/by Hannah Flanders
https://www.wisbank.com/wp-content/uploads/2023/06/Legal-scaled.jpeg 1707 2560 Hannah Flanders https://www.wisbank.com/wp-content/uploads/2021/09/Wisconsin-Bankers-Association-logo.svg Hannah Flanders2023-10-03 08:11:472023-10-03 08:11:47Compliance Column: A Refresher on Rescission Rules
Compliance, News

Executive Letter: Federal Judge in Texas Delays Section 1071 Mandatory Compliance Dates for Some

By Rose Oswald Poels

Through an order issued earlier this week, a federal judge in the U.S. District Court, Southern District of Texas, McCallen Division enjoined implementation and enforcement of the Bureau of Consumer Financial Protection’s (CFPB) Section 1071 Small Business Data Collection and Reporting Rule while the United States Supreme Court hears a challenge to CFPB’s funding structure. This enjoinment however does not apply to all banks.

The American Bankers Association (ABA), Texas Bankers Association (TBA), and Rio Bank of McAllen, Texas (collectively, the plaintiffs) had jointly filed a lawsuit against CFPB earlier this spring seeking an injunction for all lenders covered by the rule. The plaintiffs requested the court enjoin the Section 1071 rule nationwide until the U.S. Supreme Court resolves the constitutionality of CPFB’s funding structure.

In 2022, the Fifth Circuit held CFPB’s funding structure unconstitutional because Congress funded CFPB directly from the Federal Reserve; such funding contradicts the Constitution’s Appropriations Clause. CFPB appealed the Fifth Circuit’s decision. See CFPB v. Community Financial Services Association of America. The U.S. Supreme Court agreed to take up the case; however, the Supreme Court is not scheduled to hear arguments until October. A decision by the Supreme Court could be released any time before the end of June 2024. These dates are very close to mandatory implementation of the Section 1071 rule — which for some banks begins as soon as October 2024.

As mentioned above, the federal Texas judge enjoined implementation and enforcement of CFPB’s Section 1071 rule. Unfortunately, however, the court denied the plaintiff’s request for nationwide injunctive relief. The order only applies to the plaintiffs’ members. As a result, the relief only applies to ABA members, TBA members, and to Rio Bank.

I am currently in discussion with outside counsel regarding the narrowness of the order and whether other steps may be taken to help find relief for WBA-member banks not covered by the order. I encourage banks that have yet to determine applicability of Section 1071 to the bank to determine whether and when it must comply with Section 1071, as applicable.

As a reminder, implementation of the Section 1071 rule is staggered. Banks that originate more than 2,500 covered credit transactions in each of the two preceding calendar years must comply with the rule no later than October 1, 2024; banks that originate less than 2,500 but at least 500 covered credit transactions in each of the two preceding calendar years must comply no later than April 1, 2025; and banks that originate less than 500 but at least 100 covered credit transactions in the previous two calendar years must implement by January 1, 2026.

A covered credit transaction is one that meets the definition of “business credit” under Regulation B unless the credit is specifically excluded by the Section 1071 rule. Agricultural purpose loans are included in the Regulation B definition. Specifically excluded credit from the definition of a covered credit transaction under Section 1071 are: trade credit, HMDA-reportable transactions, insurance premium financing, public utility credit, securities credit, incidental credit, factoring, and leases, as defined by the rule. The ability to exclude HMDA-reportable transactions from the definition of covered credit transaction applies to both HMDA-reporting and non-HMDA reporting banks.

Read the Order
August 3, 2023/by Hannah Flanders
https://www.wisbank.com/wp-content/uploads/2021/09/Triangle-Backgrounds_Blue-on-Lime-Green.jpg 972 1920 Hannah Flanders https://www.wisbank.com/wp-content/uploads/2021/09/Wisconsin-Bankers-Association-logo.svg Hannah Flanders2023-08-03 07:25:592023-08-03 07:25:59Executive Letter: Federal Judge in Texas Delays Section 1071 Mandatory Compliance Dates for Some
Search Search

Categories

  • Advocacy
  • Community
  • Compliance
  • Credit Unions
  • Education
  • Member News
  • News
  • Products
  • Resources
  • Uncategorized

Recent Posts

  • Chair’s Message: Education: Our Industry’s Best Investment
  • Prevail Bank Supports CASA of Marathon County with a $5,000 Donation
  • Prevail Bank Supports St. Vincent de Paul with a $10,000 Donation
  • Susan Hauke Celebrated 35 Years at National Exchange Bank & Trust
  • Tonya Olson Joins Prevail Bank as Mortgage Loan Originator

Archives

  • November 2026
  • October 2026
  • September 2026
  • August 2026
  • July 2026
  • June 2026
  • May 2026
  • April 2026
  • March 2026
  • February 2026
  • January 2026
  • December 2025
  • November 2025
  • October 2025
  • September 2025
  • August 2025
  • July 2025
  • June 2025
  • May 2025
  • April 2025
  • March 2025
  • February 2025
  • January 2025
  • December 2024
  • November 2024
  • October 2024
  • September 2024
  • August 2024
  • July 2024
  • June 2024
  • May 2024
  • April 2024
  • March 2024
  • February 2024
  • January 2024
  • December 2023
  • November 2023
  • October 2023
  • September 2023
  • August 2023
  • July 2023
  • June 2023
  • May 2023
  • April 2023
  • March 2023
  • February 2023
  • January 2023
  • December 2016
Wisconsin Bankers Association logo
  • About
  • Community
  • Subsidiaries
  • Staff

questions@wisbank.com

608-441-1200

4721 S Biltmore Ln.
Madison, WI 53718

Get our Newsletter!
Subscribe

© 2025 Wisconsin Bankers Association. All rights reserved. | Website Design by Bizzy Bizzy
Scroll to top Scroll to top Scroll to top

This site uses cookies. By continuing to browse the site, you are agreeing to our use of cookies.

OKLearn more×

Cookie and Privacy Settings


How we use cookies

We may request cookies to be set on your device. We use cookies to let us know when you visit our websites, how you interact with us, to enrich your user experience, and to customize your relationship with our website.

Click on the different category headings to find out more. You can also change some of your preferences. Note that blocking some types of cookies may impact your experience on our websites and the services we are able to offer.

Essential Website Cookies

These cookies are strictly necessary to provide you with services available through our website and to use some of its features.

Because these cookies are strictly necessary to deliver the website, refusing them will have impact how our site functions. You always can block or delete cookies by changing your browser settings and force blocking all cookies on this website. But this will always prompt you to accept/refuse cookies when revisiting our site.

We fully respect if you want to refuse cookies but to avoid asking you again and again kindly allow us to store a cookie for that. You are free to opt out any time or opt in for other cookies to get a better experience. If you refuse cookies we will remove all set cookies in our domain.

We provide you with a list of stored cookies on your computer in our domain so you can check what we stored. Due to security reasons we are not able to show or modify cookies from other domains. You can check these in your browser security settings.

Other external services

We also use different external services like Google Webfonts, Google Maps, and external Video providers. Since these providers may collect personal data like your IP address we allow you to block them here. Please be aware that this might heavily reduce the functionality and appearance of our site. Changes will take effect once you reload the page.

Google Webfont Settings:

Google Map Settings:

Google reCaptcha Settings:

Vimeo and Youtube video embeds:

Privacy Policy

You can read about our cookies and privacy settings in detail on our Privacy Policy Page.

Terms of Use
Accept settingsHide notification only

Subscribe

* indicates required


Membership