• Home
  • Education
  • News and Resources
  • Advocacy
  • Associate Members
  • Contact
  • My Profile
  • Click to open the search input field Click to open the search input field Search
  • Menu Menu

Tag Archive for: Wisconsin Banker

Posts

Advocacy, Member News

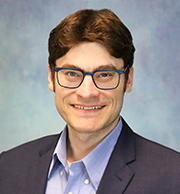
Chair’s Column: Why Advocacy Matters — Now More Than Ever

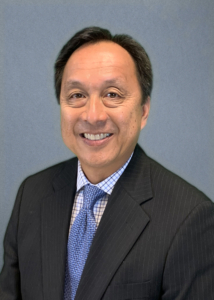
Paul Northway

Paul Northway

By Paul Northway

It was a pleasure to either meet or reconnect with so many members at the Annual WBA Chair’s Member Appreciation Golf Outing on August 14 at Trapper’s Turn Golf Club. In addition to it being a fun event, it underscores how much the WBA Board values the active participation of our bank and associate members. Thank you for your membership.

As community bankers, we wear a lot of hats. We serve customers, support our teams, lead our organizations, and stay on top of everything from regulations to technology. But one responsibility that sometimes flies under the radar, but shouldn’t, is our role as advocates for the industry we love.

Advocacy may not always be top of mind, but it’s one of the most important things we can do to protect and advance community banking in Wisconsin. Why? Because if we don’t tell our story, someone else will — and chances are, they won’t get it right.

When we engage in advocacy — whether that’s attending Capitol Day, traveling to Washington, D.C., hosting a legislator for a Take Your Legislator to Work Day, (TYLTWD) or even just picking up the phone to share how a proposed regulation might affect your bank — we strengthen the relevance and resilience of our industry. We remind lawmakers that community banks are essential to the health of our local economies. We fund small businesses, support local farmers, and provide financial guidance to our neighbors. That is not a story that should be left untold

Advocacy also plays a vital role in shaping a regulatory environment that works for us, not against us. Without our voices in the room, there is a real risk that laws and regulations will be written with only the largest institutions in mind which can create burdens that don’t fit the scale or mission of community banks. When we speak up, we help make sure the community bank model is protected and allowed to thrive.

One of the simplest and most effective ways your bank can stay engaged is by designating an Advocacy Officer. Advocacy Officers help coordinate outreach and keep their bank informed about key legislative and regulatory issues. It doesn’t require a political science degree, only a willingness to help tell our story.

Events like Capitol Day and trips to Washington, D.C. with the American Bankers Association or the Independent Community Bankers of America are great opportunities to build relationships with elected officials and make sure they know who we are and what matters to us. These connections don’t just help our industry, they help our communities by ensuring our policymakers understand the real-world impact of their decisions.

Don’t forget — advocacy isn’t just for CEOs. In fact, it’s even more powerful when a broad range of voices are involved. Every banker has a story to tell, and every story helps paint a clearer picture of the industry’s relevance in our state.

The bottom line is this: advocacy amplifies our voices, protects what makes community banking special, and helps ensure a strong future for our industry. I encourage you to take the next step: name an advocacy officer: attend Capitol Day; host a TYLTW event; register for the upcoming Milford Hills Outing, or simply reach out to learn more about how you can support WBA.

Our fundraising goal for 2025 is to raise $300,000 for WBA’s Wisbankpac (PAC) and Alliance for Bankers Conduit (ABW). The dollars raised for advocacy will help ensure our message is loud and clear in Madison and Washington as we continue to keep community banking relevant by shaping legislation that lessens regulatory burden and aims to level the playing field with competitors such as the credit unions and other non-traditional banks entering our space. I am asking for your support in achieving this important goal of raising $300,000.

I should note that WBA staff recently held a “WBA Mini-Golf Challenge” themed staff advocacy campaign organized by the WBA government relations team (Lorenzo Cruz and Tyler Foti) to support PAC and ABW. WBA staff collectively raised over $14,197 which exceeded the Association’s goal of $12,500. As WBA President and CEO Rose Oswald Poels says, supporting pro-banking political candidates is not about “D” or “R” for political affiliation, but instead it is “B” for the “Banking” Party.

Northway is president and CEO of American National Bank Fox Cities and the 2025–2026 WBA Chair.

September 9, 2025/by Katie Reiser
https://www.wisbank.com/wp-content/uploads/2021/09/Triangle-Backgrounds_Yellow-on-Light-Blue.jpg 972 1921 Katie Reiser https://www.wisbank.com/wp-content/uploads/2021/09/Wisconsin-Bankers-Association-logo.svg Katie Reiser2025-09-09 07:58:222025-09-09 07:58:22Chair’s Column: Why Advocacy Matters — Now More Than Ever
Community, Member News, News

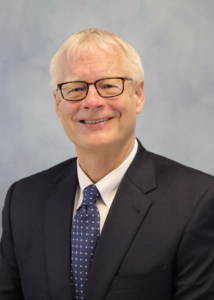
Community Advocate Spotlight: Northern State Bank President John H. Beirl

The following is a brief interview between WBA President and CEO Rose Oswald Poels and President of Northern State Bank in Ashland John H. Beirl.

John H. Beirl

Rose: How did you first get into the banking industry?
John: I mostly credit my education, at the University of Wisconsin – Madison, for my banking career. Neither of my parents were college grads. My mother was a secretary. My father was … well honestly … an alcoholic. Early on, I realized my only ticket out and up would be through a good education.

I couldn’t afford private college or out-of-state tuition, so I opted for Madison. First Wisconsin – Madison was my first banking job after obtaining my MBA. After First Wis, I continued to learn through positions at First of America – Michigan and NorthLand Bank of Wisconsin. Throughout my career, I have held many titles; branch manager (yes, with teller duties), consumer, mortgage, commercial lender, chief loan officer, and president.

After years away, I was offered a position to come back home — to work at the last remaining community bank in Ashland; Northern State Bank. I am living proof that you can go home again.

What is your favorite aspect of your role at the bank?
I value building relationships with my customers, fellow employees, supporting entities, and our community. Strong customer relationships are the foundation of community banking. I know the people in my hometown. A lot of them are my customers. I know their families. I know their life stories. Over the years, we’ve built a confident trust. They know I will be there for them … offering sound and honest financial options.

My fellow workers are my second family. I spend more of my waking hours with them, than I do at home. We are on the same team. We share our lives.

Building relationships with key external support partners and vendors helps us provide quality customer service. We cannot do everything internally. We form bonds with people and organizations we know we can rely on.

When our community improves, we all do better. I grew up in Ashland. My roots run deep. I volunteer … lots. We are in this together.

What do you wish the general public understood about the banking industry?
Community banking is built on trust. Most community bankers are not paid on commission. We do well when our customers succeed. Community bankers listen and match our products and services to wants and needs – to make lives better. It’s what we do. It sets us apart.

Where do you believe the industry’s greatest challenges are in the next three to five years?
I believe community banks’ greatest challenges are succession planning and finding good people who will be committed to our industry.

Do we have qualified people who will continue to carry the torch? If not, where will they come from? What about the work ethic?

Please describe your current role at your bank and share with us one of your more rewarding experiences (e.g., A time you had to go above and beyond to help a customer, a memorable customer interaction, stepping in to help the local community after a disaster, or something more personal, etc.).
I view my current role as managing, mentoring, and transferring longstanding relationships. Managing and mentoring means accepting change yet acknowledging and honoring the values, processes, and procedures that got us here … and made us successful.

Transferring my customer relationships will require both time and great care. My loan portfolio was sizeable and built over decades. Our customers are our greatest assets.

When I was grade school age, my mother worked as a loan secretary at Northern State Bank. We lived on the east side of Ashland and the Little League parks were on the west side. The bank is smack-dab in the center of town. Almost every day, a group of us sandlot kids would ride our banana bikes
to play baseball. After many a hot summer games, we would bicycle home and stop at the bank for a drink of cold water (at their water fountain) and I’d say “Hi!” to mom.

My mother retired in 1984 and was diagnosed with breast cancer that same year. She passed, after an anguishing battle, six years later. She would never live to see her son come back home and become President of Northern State Bank. Miss you, Mom!

Do you know a banker who should be recognized as a Community Advocate for the work that they do? Nominate them today by emailing Rose at ropoels@wisbank.com!

July 29, 2025/by Katie Reiser
https://www.wisbank.com/wp-content/uploads/2021/09/Wisconsin-Bankers-Association-logo.svg 0 0 Katie Reiser https://www.wisbank.com/wp-content/uploads/2021/09/Wisconsin-Bankers-Association-logo.svg Katie Reiser2025-07-29 07:37:342025-07-29 08:48:23Community Advocate Spotlight: Northern State Bank President John H. Beirl
Member News, News

Strategic Connections: The Power of Intentional Networking

By Josh Effinger

Josh Effinger

Networking is a great tool for sales focused teams to acquire new business, but it’s also important to instill that culture into everyone in the organization, especially the marketing department. When you make networking intentional, it connects you to fresh ideas, local partnerships, and peer support. It can also align the marketing and sales teams to work better together.

1. Network with Your Own Team
Developing powerful relationships with your front-line colleagues will give you valuable insights from those working directly with the customers. They know what drives sales, generates interest, and what questions or pain points are trending.

•  Attend internal meetings outside your focus
•  Go on a sales or service call with a banker
•  Network directly with customers and find ways to provide extra value for them and leverage that time to get testimonials and feedback

Regularly connecting will give you real time feedback on marketing initiatives. It will also help align messaging and strategy across departments throughout the bank.

2. External Networking
Networking outside of the bank is an opportunity for marketing professionals to build their network and get more out of their marketing budget.

•  Attend events hosted by your local Chamber of Commerce, small business alliances, or other community organizations
•  Get involved by joining a committee or board of directors for a local organization, event or non-profit
•  Connect regularly with other marketing peers to collaborate on ideas
•  Practice a “sales” mentality on behalf of the bank by asking for business

Networking allows you to grow both personally and professionally. The more you network, the more effectively you can position your institution for growth.

For a marketing professional at a community bank, the value of strong relationships cannot be overstated. Building connections within your own team fosters collaboration and alignment, while external networking opens doors to new ideas, partnerships, and opportunities. Intentionally investing in networking can lay the foundation for both personal development and the long-term strength of your bank’s marketing efforts.

Josh Effinger is marketing officer at Ixonia Bank and member of the 2025–2026 WBA Marketing Committee.

July 28, 2025/by Katie Reiser
https://www.wisbank.com/wp-content/uploads/2021/09/Triangle-Backgrounds_Yellow-on-Light-Blue.jpg 972 1921 Katie Reiser https://www.wisbank.com/wp-content/uploads/2021/09/Wisconsin-Bankers-Association-logo.svg Katie Reiser2025-07-28 08:02:002025-07-28 08:02:00Strategic Connections: The Power of Intentional Networking
News

Understanding the Impact of Quantum Computing and AI on Cybersecurity

By Rob Foxx

The topics of quantum computing and AI are often new and confusing—and unfortunately, they haven’t been well explained to many people. However, these technologies are already changing the ways in which attackers gain access to systems and data.

According to a recent report by Mimecast, 95% of breaches are caused by human error. This staggering figure highlights the critical importance of training your staff as a core part of any cybersecurity strategy. These errors typically occur because someone or something appeared legitimate enough to prompt user action. This allows attackers to bypass most traditional security controls, since the malicious action is performed by an authorized user. As technology continues to evolve, we can expect human error to play an even greater role in future breaches.

How Quantum Computing Changes the Game
Before diving into its implications, it’s important to define what quantum computing actually is. Traditional computers use binary logic, representing data as either a 1 or a 0. In contrast, quantum computers leverage qubits, which can represent 1 and 0 simultaneously through a principle called superposition. This allows quantum computers to evaluate many possibilities at once, significantly accelerating complex computations.

While quantum computing demands more power and specialized hardware, its speed poses a serious threat to current cybersecurity defenses. For example, tasks like reversing a hash (e.g., an encrypted password) — which would take traditional computers days, weeks, or even years — can potentially be performed in a fraction of the time using quantum technology.

Quantum computing can also enable more sophisticated malware, especially under ransomware-as-a-service models, and may dramatically accelerate the discovery of zero-day vulnerabilities — making patching and proactive defense more critical than ever.

The Role of AI in Evolving Threats
Artificial Intelligence, at this point, should be a familiar concept. AI consumes vast amounts of data, analyzes it, and uses that as a foundation to learn, reason, and solve problems. While it’s far from perfect, AI has become a powerful tool — especially for bad actors.

Cybercriminals are now using AI to improve their research, enhance targeted phishing, and execute more convincing social engineering attacks. With access to better, more personalized data than ever before, AI-generated threats can appear highly authentic — even to seasoned users.

Additionally, AI can be used to create ransomware faster, with greater effectiveness, and with less technical skill required than in the past. These advantages make AI an indispensable tool for attackers — and a growing concern for defenders.

What You Can Do
The most important thing you can do today is educate your team and ensure you have access to cybersecurity experts who can help manage these risks. Strong security practices are more critical than ever, including:
•  Longer passwords, as recommended by National Institute of Standards and Technology (NIST)
•  Multi-factor authentication (MFA) for system access
•  Continuous logging and review of activity within your environment

In addition, legacy tools are no longer sufficient on their own. Many environments now require upgraded solutions, such as:
•  Next-generation antivirus (NGAV)
•  Managed Detection and Response (MDR) services from providers like Cynet 360, CrowdStrike, and SentinelOne

These solutions can analyze logs, detect threats, and issue alerts far more quickly than human analysts ever could. They typically cover:
•  User behavior analytics
•  System and process monitoring
•  Network traffic inspection
•  File and endpoint analysis

Most importantly, these tools are also AI-powered, allowing them to defend against AI-driven attacks using similar technology. In the rapidly evolving cybersecurity landscape, staying ahead means adopting the same tools and techniques your adversaries are using — and doing it before they do.

Foxx is director – infosec and IT audit services for FIPCO, a WBA Gold Associate Member.

July 18, 2025/by Katie Reiser
https://www.wisbank.com/wp-content/uploads/2021/09/Wisconsin-Bankers-Association-logo.svg 0 0 Katie Reiser https://www.wisbank.com/wp-content/uploads/2021/09/Wisconsin-Bankers-Association-logo.svg Katie Reiser2025-07-18 08:23:532025-07-18 08:23:53Understanding the Impact of Quantum Computing and AI on Cybersecurity
Compliance, News

Acceptable Forms of Customer ID for CIP Purposes

By Scott Birrenkott

While there have been no changes to Customer Identification Program (CIP) requirements, WBA legal is frequently asked: what forms of identification are acceptable for purposes of verifying a customer’s identity? The short answer is that it depends on bank policy. Meaning that theoretically, any form of ID could potentially be used to verify a customer’s identity, and meet CIP requirements.

In order to understand why, it helps to start with the basics of CIP. As part of compliance with Bank Secrecy Act (BSA) regulatory requirements, banks must have a written CIP policy. The more specific components are that a CIP policy must include risk-based procedures to verify the identity of each customer at account-opening. At a minimum, each program must obtain the name, date of birth, address, and identification number from each customer. This information must be verified, using documentary, non-documentary, or a combination of both methods, depending on bank’s procedures.

When relying upon documentary methods to verify a customer’s identity, a bank’s policy must specify which documents to obtain. Similarly, if procedures permit non-documentary methods, a bank’s procedures must specify which methods to use. A bank need not establish the accuracy of every element of identifying information obtained, but it must verify enough information to form a reasonable belief that it knows the true identity of the customer. For most customers who are individuals, banks typically review an unexpired government-issued form of identification evidencing a customer’s nationality or residence and bearing a photograph or similar safeguard. Non-documentary methods may include contacting a customer, or otherwise independently verifying the customer’s identity through other sources.

BSA requirements don’t get much more specific than that. Meaning, they don’t specify which forms of identification can or cannot be used. After all, banks can use documentary or non-documentary methods. A non-documentary method, for example, being the fact that a customer might be a neighbor of yours. Whether a bank can verify a customer’s identity based on the fact that they are an employee’s neighbor isn’t addressed by BSA directly – it’s addressed by bank policy. The same applies to documentary methods. Meaning, all forms of verification depend on bank policy, and thus which forms of identification are acceptable for CIP purposes fully depends on each bank’s CIP policy.

As described previously, perhaps the most common form of verification is a driver’s license. However, that’s not the only acceptable form of identification. Any form of identification which meets the considerations above and, ultimately, bank’s CIP policy is potentially an acceptable form of identification. In consideration of this, banks may encounter unique forms of identification. In addition to a state-issued driver’s license or other state-issued ID card, some examples include a passport or alien ID card. There are also a variety of forms issued by the United States Citizenship and Immigration Services. For example, the U.S. Department of Homeland Security may provide certain records to refugees or asylees, who may also possess identification documents through the United States Citizenship and Immigration Services. These, and other forms of identification may be acceptable for CIP purposes if bank policy permits. Lastly, don’t forget the possibility of non-documentary methods. The types of verification a bank uses will be tailored to its risk considerations and, likely, its customer base. For example, if a bank serves a community with an Amish population, it may encounter customers who don’t have any form of physical identification at all. In these situations, and others, consider what bank policy requires in order to properly identify and verify customers.

Birrenkott is the WBA director – legal

July 16, 2025/by Katie Reiser
https://www.wisbank.com/wp-content/uploads/2021/09/Triangle-Backgrounds_Dark-Blue-on-Light-Blue.jpg 972 1921 Katie Reiser https://www.wisbank.com/wp-content/uploads/2021/09/Wisconsin-Bankers-Association-logo.svg Katie Reiser2025-07-16 07:23:182025-07-16 07:23:18Acceptable Forms of Customer ID for CIP Purposes
Member News

Chair’s Column — Relevance in a Changing World: A Vision for Community Banks and WBA

Paul Northway

Paul Northway

On June 11, I was incredibly honored to be installed as Chair of the WBA Board of Directors. During the ceremony at the WBA office, we welcomed new board members and expressed our gratitude to those who completed their terms.
A special thanks goes to our outgoing chair, Al Araque, SVP and director of consumer, private, and business banking at Johnson Financial Group in Racine. His leadership and passion generated a lot of positive momentum for the Association. Al’s theme during his term was “impact,” and you’ll see in the Year in Review section of this issue just how much WBA and its members have accomplished.

When I thought about the theme I wanted to focus on this year, the word “relevance” really stood out. Community banks are deeply relevant — we champion small businesses, support local farmers, and serve as trusted partners in our communities. Relevance is also about leadership and building companies that focus on the people and not just the numbers.

I met with WBA staff after the installation and spoke about a few of the ways I see relevance showing up in our work.

In Community Banking
•  Meeting customers where they are
Community banks stay relevant by keeping up with evolving customer expectations. Whether it’s through mobile banking, digital tools, or continuing to deliver a personal touch, we remain competitive by staying flexible and responsive.
•  Supporting local economies
We play a visible role in our communities by providing small business loans, agricultural financing, and financial education. Our presence makes a difference — and that keeps us relevant.
•  Growing our teams
When banks invest in leadership development, mentorship, and education, they show their teams that banking isn’t just a job — it’s a long-term career with purpose and meaning.

At the Association Level
•  Speaking up for the industry
WBA’s advocacy work is a big part of staying relevant. Whether it’s at the Capitol in Madison or in D.C., we make sure lawmakers understand how their decisions affect banks and the people we serve.
• Delivering tools and professional development opportunities that matter
WBA keeps members up to speed with training, compliance support, and leadership programs that reflect what’s happening in the industry right now (and what’s coming down the pike).
•  Helping bankers connect
Programs like WBA Connect Peer Groups and BOLT give bankers across the state a chance to learn from each other, share ideas, and work through challenges together.
•  Balancing innovation with our roots.
Relevance doesn’t mean jumping on every new trend. It means knowing when and how to adopt change in a way that continues to honor what community banking is all about — relationships, service, and trust.

I’m excited for the year ahead and grateful to be working alongside all of you, WBA President and CEO Rose Oswald Poels, and the entire WBA team as we continue to move our industry forward.

July 14, 2025/by Katie Reiser
https://www.wisbank.com/wp-content/uploads/2021/09/Triangle-Backgrounds_Yellow-on-Light-Blue.jpg 972 1921 Katie Reiser https://www.wisbank.com/wp-content/uploads/2021/09/Wisconsin-Bankers-Association-logo.svg Katie Reiser2025-07-14 08:13:542025-07-14 08:13:54Chair’s Column — Relevance in a Changing World: A Vision for Community Banks and WBA
News, Resources

Inside the Fight Against Fraud: Highlights From WBA’s First Fraud Summit

By Katie Reiser

As fraud becomes more prevalent and complex, many Wisconsin bankers voiced the need for more practical insights and support. In response, the Wisconsin Bankers Association (WBA) hosted its first Fraud Summit on June 3, 2025. The one-day event brought bankers together to dig into today’s biggest fraud threats and how to fight back — from cyberattacks and scams to regulatory changes and prevention tactics. The summit was created based on direct input from members who said they needed more resources to stay ahead of fraud trends. Strong turnout and engaged discussion underscored how relevant the event was, and based on early and enthusiastic feedback, WBA is exploring hosting another Fraud Summit in the future.

Bankers Reflect on Takeaways and Impact
Two attendees from Wolf River Community Bank shared their feedback from the Summit. Diane Moen-Ross, electronic banking supervisor, said, “I found the Fraud Summit to be both entertaining and insightful. I had a few things make me really think about my day-to-day habits and look at things differently from a security level for the bank after hearing from the speakers. I found the information they shared to be helpful in protecting the bank and looking out
or our customers.” She added, “I also enjoyed the humor they put into their presentations.”

Her colleague Kyra Baeten, BSA & risk analyst, offered this take, “The summit was amazing, and I was truly in my element! It exceeded my expectations in every way. The presenters were raw, real, and incredibly insightful, which went beyond just surface level discussions. It pushed me to think beyond my current ‘fraud box’ and how to better protect myself, my institution, and the communities we serve.” She summarized her experience, “I left feeling inspired, energized, and already looking forward to next year’s Summit!”

SHAZAM’s Kern: How Froud Follows Shifting Payment Trends
In the opening session, “Where Payments Go, Fraud Will Follow,” Diana Kern, AAP, senior financial solutions consultant at SHAZAM, explored how changing consumer payment habits are driving new fraud risks. For the first time, cash is no longer the most common method for purchases under $25, according to the Federal Reserve’s 2024 Diary of Consumer Payment Choice. Card payments now lead the way, and nearly half of person-to-person payments are made through mobile apps.

Kern walked attendees through how debit transactions have evolved — from magnetic stripe to chip and contactless cards, from physical cards to digital wallets, and from card-present to card-not-present (CNP) scenarios. These changes have big implications. In 2024, 98% of debit card fraud reported by SHAZAM clients occurred in CNP environments.

She pointed to BIN attacks, account probing, and fraud targeting specific merchant codes (like digital goods and money transfer services) as key issues. While chip technology has helped reduce counterfeit fraud, fallback transactions using magnetic stripes remain vulnerable.

Kern stressed the value of layered fraud defenses, such as real-time blocking, cardholder alerts, and well-calibrated decline rules. She also noted that data breaches — even those unrelated to payments — can give scammers the fuel they need to launch convincing social engineering attacks.

ABA’s Smith: Social Engineering, Check Fraud, and AI Threats
Patrick Smith, senior vice president of fraud operations with the American Bankers Association (ABA), gave an overview of current fraud challenges, including social engineering, check fraud, and emerging risks tied to artificial intelligence.
Smith made it clear that while banks are doing more than any other sector to protect consumers, they can’t do it alone. Responsibility must also be shared by telecom companies, social media platforms, and lawmakers.

He noted that social engineering scams have become harder to detect. Many now mimic trusted environments, build rapport with victims, and create a sense of urgency — making them highly effective. Check fraud, meanwhile, continues to grow despite a downturn in check use, now accounting for 66% of payment fraud. Mail theft and counterfeit or altered checks are key drivers.

AI is making an already complex fraud landscape even more challenging. Smith cited examples like deepfakes (providing a chilling example of how easy it is to clone voices), spoofed identity checks, and realistic fake IDs, all of which make scams faster to perpetuate and more convincing. He urged banks to continue building robust defenses by ensuring their teams are familiar with current threats and working closely with trusted vendors.

Smith shared that ABA is calling for a national fraud prevention strategy that includes establishing a White House Office of Fraud and Scam Prevention, increasing FCC enforcement regarding customer reported spam texts, and bringing in state and local law enforcement to improve prosecution rates.

Iannarelli: Cyber Vigilance in a High-Risk Environment
Former FBI Special Agent John Iannarelli, Esq., CSP (aka FBI John) gave a candid assessment of the cybersecurity landscape. According to the Identity Theft Resource Center, last year set records for data breaches, with over 15 billion records compromised.

Top threats include identity theft, phishing, ransomware, business email compromise (BEC), Internet of Things (IoT which are the internet-connected devices embedded in everyday objects which are sending and receiving data), and mobile-device related fraud. According to an FBI report, BEC alone cost U.S. businesses $2.4 billion last year, with cases up 270%. Iannarelli referenced the 2024 ransomware attack on Patelco Credit Union as a reminder of the financial and reputational damage such events can cause.

He also flagged the role of AI deepfakes in expanding cyber risk, highlighting a $25 million fraudulent wire transfer driven by a deepfake impersonation. Still, he warned that internal threats remain significant. About 75% of breaches are tied to insiders — often well-meaning but untrained employees.

To help reduce exposure, Iannarelli encouraged banks to focus on staff training, establish strong policies, use multifactor authentication, and maintain a tested incident response plan.

Ayotte: Stop Social Engineering Before It Starts
Michael Ayotte, senior cybersecurity consultant with Wipfli LLP and U.S. Special Forces veteran, focused on the human side of fraud — particularly how scammers manipulate people, not just systems. He explained how criminals often start with publicly available data from sources like obituaries, social media, and bank websites to piece together convincing identities.

Ayotte reminded attendees that identity verification processes should never give away clues. “Never disclose account numbers over the phone,” he said. If a caller can’t be verified, staff should direct them to a branch.

His session also highlighted common phishing tactics: urgency, secrecy, unusual grammar, and lookalike email addresses from company executives. Ayotte recommended physical security protocols too — from screening vendors to checking IDs — and stressed the need for ongoing training and internal testing through simulated phishing and security drills. He shared his own experiences conducting physical security audits for clients that were eye-opening and likely prompted many attendees to review their workplace policies.

His message was clear: it is crucial to empower employees to act on suspicious activity even though their focus is typically on customer service. There needs to be a balance between the two. Policies and technology matter, but awareness and a questioning mindset when something seems off are just as critical.

What’s Next?
WBA plans to follow up with a future article sharing practical tips and takeaways from the Summit, with additional insights from WBA’s Director – Legal, Scott Birrenkott. Birrenkott will share how Wisconsin banks can apply these lessons in the face of shifting fraud risks. Birrenkott
commented, “A lot of great information was shared at the WBA Fraud Summit. It just goes to show the value of gathering and sharing information. WBA will continue to provide updates and resources to help banks tackle the challenge of staying one step ahead of criminals.”

July 11, 2025/by Katie Reiser
https://www.wisbank.com/wp-content/uploads/2021/09/Triangle-Backgrounds_Yellow-on-Light-Blue.jpg 972 1921 Katie Reiser https://www.wisbank.com/wp-content/uploads/2021/09/Wisconsin-Bankers-Association-logo.svg Katie Reiser2025-07-11 08:24:212025-07-11 08:24:21Inside the Fight Against Fraud: Highlights From WBA’s First Fraud Summit
Member News, News

Association Update: Staying Relevant in a Rapidly Changing Industry

By Daryll Lund

The start of the Wisconsin Bankers Association’s (WBA) new fiscal year is a great time to spotlight the many opportunities available for both new and experienced bankers to grow professionally and connect with others in the industry. Representing over 30,000 bankers statewide, WBA is powered by its members’ energy, insight, and commitment to working together.

On June 11, 2025, Paul Northway, President and CEO of American National Bank Fox Cities, was installed as Chair of WBA’s Board of Directors. With a focus on relevance, Northway’s message to members is clear: staying connected, engaged, and forward-thinking is essential for the association — and the industry — to thrive. As the banking landscape continues to evolve, it’s up to all of us to ensure WBA remains a trusted, valuable resource for years to come.

A key opportunity is the WBA Advocacy Officer program. These individuals serve as liaisons between their banks, WBA, and policymakers. By sharing how legislation affects their businesses and communities, Advocacy Officers play a crucial role in helping lawmakers understand the real-world impact of their decisions.

WBA’s professional development and engagement opportunities are designed to keep our members informed and well-prepared to face the evolving issues in our industry.
Each year, WBA hosts 75 in-person events, conferences, and schools across Wisconsin, in addition to convenient virtual programs. These gatherings connect bankers to expert insights, practical tools, and each other.

Leadership development remains a top priority. Our Building Our Leaders of Tomorrow (BOLT) program, now in its 12th year, helps emerging leaders grow their skills and confidence. Through events and mentorship, BOLT participants are shaping the future of Wisconsin’s banking industry.

WBA is also committed to peer connection. WBA Connect offers focused peer networking groups for everyone from HR professionals to commercial lenders — providing a space to exchange ideas, solve problems, and stay sharp.

Whether you’re attending a conference, mentoring a colleague, or advocating for your bank, your engagement strengthens WBA and helps ensure WBA’s relevancy — together.

Lund is WBA executive vice president – chief of staff and president of EBC and MBIS.

July 11, 2025/by Katie Reiser
https://www.wisbank.com/wp-content/uploads/2021/09/Triangle-Backgrounds_Blue-on-Lime-Green.jpg 972 1920 Katie Reiser https://www.wisbank.com/wp-content/uploads/2021/09/Wisconsin-Bankers-Association-logo.svg Katie Reiser2025-07-11 07:52:172025-07-11 07:52:17Association Update: Staying Relevant in a Rapidly Changing Industry
Advocacy, News

Advocacy Update: The Relevance of Political Advocacy to the Banking Industry

By Lorenzo Cruz

Political advocacy is highly relevant to the banking industry in Wisconsin, as legislative and regulatory decisions significantly impact the operational landscape for banks and other financial institutions. The Wisconsin Bankers Association (WBA) is a key player in this advocacy, working to protect and advance the interests of its members.

Here are some key areas where WBA’s political advocacy is relevant to banking in Wisconsin.

1. Legislative and Regulatory Issues:
•  Protecting and advancing the industry’s interests: The WBA actively engages in government relations to influence legislative and regulatory actions, safeguarding and promoting the interests of banks, their customers, and communities.
•  Addressing key issues: The WBA advocates on crucial issues like credit card interchange fees, trust code updates, credit union powers, data privacy, and artificial intelligence.
•  Navigating budget deliberations: The WBA participates in discussions regarding the state budget that affects areas relevant to banking like the income tax exemption on commercial loans of $5 M or less which is estimated to save the banking industry over $24 M annually.

2. Supporting Pro-Banking Candidates:
•  Political action committees (PACs): The WBA utilizes PACs like Wisbankpac to support pro-banking candidates.
•  Facilitating conduit contributions: The WBA offers options like the Alliance of Bankers for Wisconsin (ABW) conduit, allowing individual bankers to support candidates of their choice.
•  Building relationships with legislators: WBA’s advocacy efforts aim to build relationships with elected officials who understand and support the banking industry.

3. Managing Political Risk:
•  Continuous engagement: The association recognizes the need for consistent engagement at all levels of government to manage political risks that could negatively impact their operations and revenues.

4. Educating the Public:
•  Issue advocacy fund: The WBA utilizes an issue advocacy fund, allowing banks to contribute corporate dollars that are pooled with other Wisconsin business coalition partners to educate the public about banking and business issues through advertising and public messaging

5. Grassroots Advocacy:
•  Encouraging participation: The WBA encourages bankers to participate in grassroots advocacy activities such as Capitol Day, PAC events, and “Take Your Legislator to Work Day.”
•  Advocacy Officers: Banks may designate Advocacy Officers to coordinate their advocacy efforts and function as liaisons with the WBA.

6. Relevant Issues Highlighted:
•  Interchange fees: Monitoring and influencing possible legislation related to credit card interchange fees.
•  Tax parity: Seeking legislative solutions to create a more level playing field for banks competing with tax-exempt institutions.
•  Data privacy: Working to protect the GLBA exemption for banks and their affiliates in the data privacy bills.
•  Crypto ATM regulations: Protecting consumers against cryptocurrency fraud by providing stronger enforcement provisions and penalties.
•  Elder fraud prevention: Advocating for robust measures to prevent and address elder fraud.
•  Trust Code modernization: Updating the trust code to remain competitive with other states.

In short, political advocacy is a vital component of WBA’s strategy, enabling the association to minimize risks by shaping the legislative and regulatory landscape, addressing critical and relevant issues, and fostering a favorable environment for WBA’s members and customers.

Thank you to the membership for your time and generous support of WBA’s advocacy efforts. Lastly for those bankers still interested in making a personal contribution to the PAC or conduit to help the government relations team meet WBA’s annual fundraising goal of $300,000, please click here. WBA is currently at 35% of the annual goal.

Cruz is WBA vice president – government relations.

July 7, 2025/by Katie Reiser
https://www.wisbank.com/wp-content/uploads/2021/09/Untitled-3_Yellow.jpg 972 1920 Katie Reiser https://www.wisbank.com/wp-content/uploads/2021/09/Wisconsin-Bankers-Association-logo.svg Katie Reiser2025-07-07 08:13:422025-07-07 08:13:42Advocacy Update: The Relevance of Political Advocacy to the Banking Industry
Member News, News

Meet DFI Secretary-designee Wendy K. Baumann

DFI Secretary-designee Wendy K. Baumann

The Wisconsin Bankers Association (WBA) recently asked Wisconsin Department of Financial Institutions (DFI) Secretary-designee Wendy K. Baumann a series of questions as a way of introducing her to members. WBA wishes Secretary-designee Baumann all the best in her new role.

What put you on the path to your profession in the financial services industry, particularly your leadership role at the Wisconsin Women’s Business Initiative Corporation (WWBIC)?

Early on in my post-secondary education and career, I found an interest in advancing what I would say is “the good” – trying to make the world a better place. My first professional position out of undergraduate college was working at Goodwill Industries and assisting underserved and lower wealth individuals obtain competitive employment. I loved it and might still be there today if my personal life had not taken me to France for a year and having a second child there. When I returned to the states, they had filled my position, so I then began work at The Council for the Spanish Speaking and also loved that, and it was there where I was introduced to commerce and the power of individuals starting or growing their own businesses. My father had owned many small businesses, too; thus, the exposure supported what I had experienced at home, but at The Council for the Spanish Speaking, I saw that problems and day-to-day issues could be overcome with not only a job but by individuals having their own money. If individuals can work – start that business and have the opportunity to do so through fair and reasonable capital – then lower income and underserved communities in essence can support themselves. I saw this strategy of economic development as more of a solution in our overall economy, and the Wisconsin Women’s Business Initiative Corporation (WWBIC) did just that – provided financial and business training coupled with fair and responsible capital to start or grow a small business.

What has been the most meaningful aspect of your career thus far?

Serving as WWBIC’s president and chief visionary officer for 31 years was truly an honor and now being appointed by Governor Tony Evers to serve the people of Wisconsin alongside fellow cabinet secretaries and Wisconsin Department of Financial Institutions (DFI) team members is an additional honor. I am grateful to be able to serve my state and continue my lifelong commitment to economic empowerment, financial inclusion, and business success for all, and especially for underserved communities and populations.

What/who inspires you and motivates your work?

Overall, it’s all about doing the right thing – providing quality and meaningful services – being part of making a positive financial impact motivates me each day. I am motivated and thankful working alongside others who carry that same sentiment of service above self. The DFI is very well run and committed to protecting the safety and soundness of Wisconsin’s financial institutions, safeguarding the investing public, facilitating commerce, and increasing financial capability throughout the state – so every person in Wisconsin has the knowledge, tools, and resources to build a stronger financial future.

How would you describe your vision for the future of DFI?

We all want an economy that is strong and vibrant for all people and families who call Wisconsin home. The strength of Wisconsin’s economy comes from its people, and an individual’s strength comes from their financial wellness. At DFI, we are committed to advancing financial literacy, access, and opportunity. We promote financial literacy, capability, and inclusion efforts for all Wisconsin residents, and provide administrative support to the Governor’s Council on Financial Literacy and Capability, which advances financial literacy and education through resources, programs, and partnerships to help Wisconsinites develop money management skills, improve credit, and plan for financial security. We encourage businesses, nonprofits, and financial institutions to promote financial education efforts, helping ensure more Wisconsinites have access to budgeting, investing, and credit-building tools, as well as retirement planning resources, homeownership support, and savings incentives. As we look forward, my goal is to ensure that Wisconsin champions financial well-being for everyone, and especially for historically underserved populations because when underserved populations thrive financially, families, businesses, and entire communities become stronger. Financial empowerment is not just about money – it is about opportunity, security, and freedom. Together, we can build a future where every person in Wisconsin has the financial knowledge, confidence, and resources to achieve their goals and dreams. I look forward to working with all of you to make this vision a reality.

What opportunities and challenges do you foresee in the coming years, and how should bankers prepare for them?

As I shared during the Wisconsin Bankers Association’s Capitol Day in early May, there are more uncertainties and curve balls ahead. Changing demographics and preferences are pushing our banks towards technological innovation. With these changes comes cost, as net interest margins are already compressed and earnings are down. These changes also introduce risk. In addition to current issues with check fraud, ATM theft, and jackpotting, there are risks with artificial intelligence, such as mimicking voice authorizations and other deepfakes. As always, cybersecurity will continue to be an ongoing concern. With new technology, there are new and more sophisticated ways for bad actors to find a way to breach a system and steal data. Finally, an ongoing concern involves recruiting talent and planning for the succession of bank management. We are seeing the challenges, especially in more rural areas, of finding the next generation of bankers for the future of these community banks. Don’t get discouraged by these challenges – keep moving forward. Our people, businesses, communities, and state depend on the continued strength and innovation of our banking industry. While we may not be able to predict the next big challenge or change on the horizon, we can count on the resiliency and adaptability of our Wisconsin banks to continue serving their customers and communities and protecting the safety and soundness of our financial institutions. Our banking leaders have repeatedly led their banks through new and ongoing challenges and changes, and I expect that the coming year will be no different. Our bankers should navigate the promise of innovation with the costs and risks, be vigilant with fraud and cybersecurity, and monitor how the changes at the federal level will impact businesses and customers in Wisconsin. By doing these things, our Wisconsin banks will continue to be a source of strength for our people, businesses, and communities.

Having served as the former chair and current co-vice chair of the Governor’s Council on Financial Literacy and Capability, could you reflect on the importance of financial education in Wisconsin?

Financial literacy and personal finance education are the keys to building a stronger financial future for individuals, families, communities, our state and collective nation. I grew up with a “spend what you can afford and save as much as you can” mindset. Many, as we know, did not have such advice and need support through our educational system, workplaces, and often later in life. The Governor’s Council on Financial Literacy and Capability and the collective efforts and strides the Council has made over the years ranks Wisconsin as one of the top states providing sound programming and support in personal finance. From the recent bipartisan legislation requiring students to take at least a one-semester course on personal finance in all our Wisconsin high schools to the recognition of teachers, policy makers, community members, bankers and the like with the annual Governor’s Financial Literacy Awards for helping Wisconsin residents build financial literacy and capability skills. Making a positive financial difference in the way individuals utilize their financial resources from young to the elderly is key to building a stronger financial future for all.

Is there anything else you would like Wisconsin bankers to know about you or your work?

DFI is dedicated to protecting the safety and soundness of Wisconsin’s financial institutions throughout the state. Our work ensures that the entities we regulate operate safely, fairly, and in compliance with state laws to protect consumers and maintain a strong financial system and economy. By ensuring our state-chartered financial institutions are safe and sound, we will continue serving the people, businesses, and communities of Wisconsin with your help. Our banks support Wisconsin residents by helping them reach their financial goals and needs and they serve as catalysts for local economic development. Together, we can help individuals and families build savings, invest in education and housing, capitalize on business opportunities, save for retirement, and cope with various economic shocks. If you would like to reach me, please email: DFISecretary@dfi.wisconsin.gov. I look forward to working with all of you!

July 1, 2025/by Katie Reiser
https://www.wisbank.com/wp-content/uploads/2021/09/Wisconsin-Bankers-Association-logo.svg 0 0 Katie Reiser https://www.wisbank.com/wp-content/uploads/2021/09/Wisconsin-Bankers-Association-logo.svg Katie Reiser2025-07-01 10:01:482025-07-21 09:16:59Meet DFI Secretary-designee Wendy K. Baumann
Page 5 of 8«‹34567›»
Search Search

Categories

  • Advocacy
  • Community
  • Compliance
  • Credit Unions
  • Education
  • Member News
  • News
  • Products
  • Resources
  • Uncategorized

Recent Posts

  • Playing Offense: The Game Plan for Core Relationship Growth in 2027
  • Is Your Leadership Keeping Up With the Culture AI Is Creating?
  • Executive Letter: Wisconsin Bankers Have a Story to Tell. Help Us Tell It.
  • Chair’s Message: Education: Our Industry’s Best Investment
  • Prevail Bank Supports CASA of Marathon County with a $5,000 Donation

Archives

  • November 2026
  • October 2026
  • September 2026
  • August 2026
  • July 2026
  • June 2026
  • May 2026
  • April 2026
  • March 2026
  • February 2026
  • January 2026
  • December 2025
  • November 2025
  • October 2025
  • September 2025
  • August 2025
  • July 2025
  • June 2025
  • May 2025
  • April 2025
  • March 2025
  • February 2025
  • January 2025
  • December 2024
  • November 2024
  • October 2024
  • September 2024
  • August 2024
  • July 2024
  • June 2024
  • May 2024
  • April 2024
  • March 2024
  • February 2024
  • January 2024
  • December 2023
  • November 2023
  • October 2023
  • September 2023
  • August 2023
  • July 2023
  • June 2023
  • May 2023
  • April 2023
  • March 2023
  • February 2023
  • January 2023
  • December 2016
Wisconsin Bankers Association logo
  • About
  • Community
  • Subsidiaries
  • Staff

questions@wisbank.com

608-441-1200

4721 S Biltmore Ln.
Madison, WI 53718

Get our Newsletter!
Subscribe

© 2025 Wisconsin Bankers Association. All rights reserved. | Website Design by Bizzy Bizzy
Scroll to top Scroll to top Scroll to top

This site uses cookies. By continuing to browse the site, you are agreeing to our use of cookies.

OKLearn more×

Cookie and Privacy Settings


How we use cookies

We may request cookies to be set on your device. We use cookies to let us know when you visit our websites, how you interact with us, to enrich your user experience, and to customize your relationship with our website.

Click on the different category headings to find out more. You can also change some of your preferences. Note that blocking some types of cookies may impact your experience on our websites and the services we are able to offer.

Essential Website Cookies

These cookies are strictly necessary to provide you with services available through our website and to use some of its features.

Because these cookies are strictly necessary to deliver the website, refusing them will have impact how our site functions. You always can block or delete cookies by changing your browser settings and force blocking all cookies on this website. But this will always prompt you to accept/refuse cookies when revisiting our site.

We fully respect if you want to refuse cookies but to avoid asking you again and again kindly allow us to store a cookie for that. You are free to opt out any time or opt in for other cookies to get a better experience. If you refuse cookies we will remove all set cookies in our domain.

We provide you with a list of stored cookies on your computer in our domain so you can check what we stored. Due to security reasons we are not able to show or modify cookies from other domains. You can check these in your browser security settings.

Other external services

We also use different external services like Google Webfonts, Google Maps, and external Video providers. Since these providers may collect personal data like your IP address we allow you to block them here. Please be aware that this might heavily reduce the functionality and appearance of our site. Changes will take effect once you reload the page.

Google Webfont Settings:

Google Map Settings:

Google reCaptcha Settings:

Vimeo and Youtube video embeds:

Privacy Policy

You can read about our cookies and privacy settings in detail on our Privacy Policy Page.

Terms of Use
Accept settingsHide notification only

Subscribe

* indicates required


Membership